The Ministry of Finance, Planning and Economic Development has assured Ugandan taxpayers that replacing the Tax Identification Number (TIN) with the National Identification Number (NIN) will not automatically create a tax obligation, emphasising that tax liability will continue to depend on applicable tax laws.
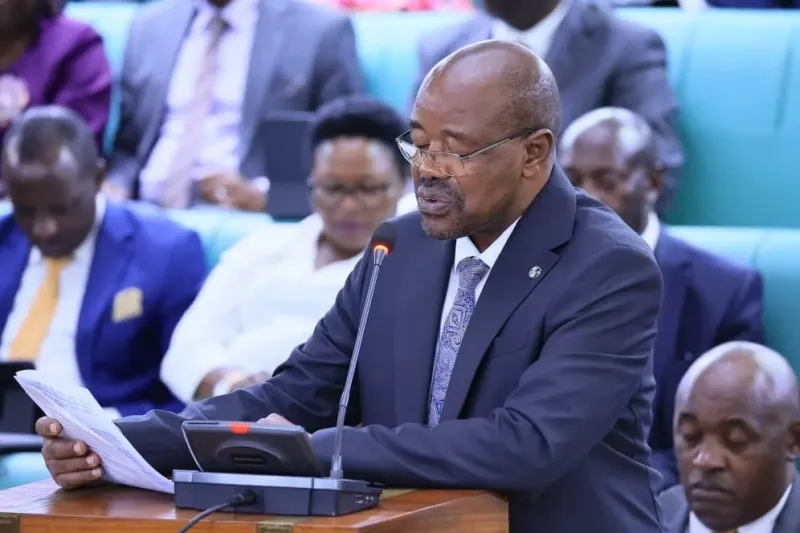
State Minister for Planning Amos Lugoloobi delivered the assurance to Parliament on behalf of the Finance Minister during Thursday’s plenary sitting chaired by Speaker Jacob Marksons Oboth.
“The NIN identifies the person. The tax law determines whether that person has a tax obligation and how much tax, if any, is payable,” Lugoloobi told Parliament.
The clarification follows the 2025 amendment to Section 4 of the Tax Procedures Code Act, which provides for the use of the NIN as the tax identification number for individual taxpayers.
The government says the transition is intended to improve taxpayer identification, eliminate duplicate records and strengthen the administration of taxes without imposing automatic tax obligations on people simply because their national identification details are linked to the Uganda Revenue Authority (URA).
According to the minister, URA’s Taxpayer Register contained approximately 5.7 million taxpayers as of June 30, 2026. Of these, about 5.4 million were individuals, although only approximately 3.3 million individual taxpayers were estimated to be active. The remaining 2.1 million records were inactive or associated with individuals who were difficult to trace.
Lugoloobi attributed some of the inconsistencies in the register to the use of separate identification numbers for national identification and tax administration, which has contributed to duplicate and inconsistent taxpayer records.
During the 2025/26 financial year, URA identified 191,813 duplicate records and 51,993 mutations in the Taxpayer Register, highlighting the need to improve the accuracy and reliability of taxpayer information.
The minister also illustrated the potential revenue implications of improving taxpayer records. He said that if the 2.1 million individuals with inactive or difficult-to-trace records were economically active and each liable to contribute an average of Shs 200,000 annually, the potential revenue would amount to approximately Shs 420 billion per year.
However, he cautioned that the figure is illustrative and should not be interpreted as actual tax revenue lost by the government. Whether an individual owes tax depends on their income, economic activity and the applicable tax laws.
The government’s efforts to improve tax administration have also been informed by findings from Uganda’s first Automatic Exchange of Information exercise conducted in September 2025. The exercise identified approximately 120,000 offshore financial accounts held by Ugandan tax residents, with a combined reported value of about Shs 7 trillion. Preliminary analysis uniquely identified approximately 20,000 taxpayers.
Under the new arrangement, the government is implementing the transition from TIN to NIN in three phases. The first involves mapping existing TINs to NINs, followed by biometric verification and updating taxpayer profiles. The final phase will involve the full transition to NIN-based taxpayer login.
As of September 30, 2026, a total of 2,130,814 NINs had been mapped to TINs out of 5,405,148 individual taxpayers. This represents approximately 39.4 per cent of the individual taxpayer register.
During the transition period, verified taxpayers will be able to access their tax accounts using either their existing TIN or their NIN. The government will determine the timing of full implementation after assessing progress in the first two phases.
Taxpayers who need to update their information can do so through URA outreach programmes, walk-in services at URA service centres and the authority’s web portal.
For companies and other registered entities, the government intends to use registration numbers issued by the Uganda Registration Services Bureau, subject to the necessary approvals. Foreign taxpayers will continue to use the applicable identification arrangements.
The reform is designed to establish a “one person, one identity” system that improves the accuracy of taxpayer records, reduces duplication, strengthens tax compliance and simplifies access to government services.
The Finance Ministry has committed to implementing the transition progressively to minimise inconvenience to taxpayers and ensure continued access to URA services.
The government’s central message is that the NIN will serve as an identification tool for individual taxpayers, while the existence and amount of any tax obligation will continue to be determined by the relevant tax laws.

Sunrise reporter
Leave a Comment
Your email address will not be published.